Protect your family’s future — starting with a conversation, not a sales pitch.
I’m Rick Larabee, a licensed life insurance professional with GFI — Global Financial Impact. I help families in California and Ohio understand their options in plain English, and choose coverage that fits their life and their budget.
Instant term life rates through Ethos — no medical exam.
Free, no-pressure review · One-on-one guidance · Serving California & Ohio
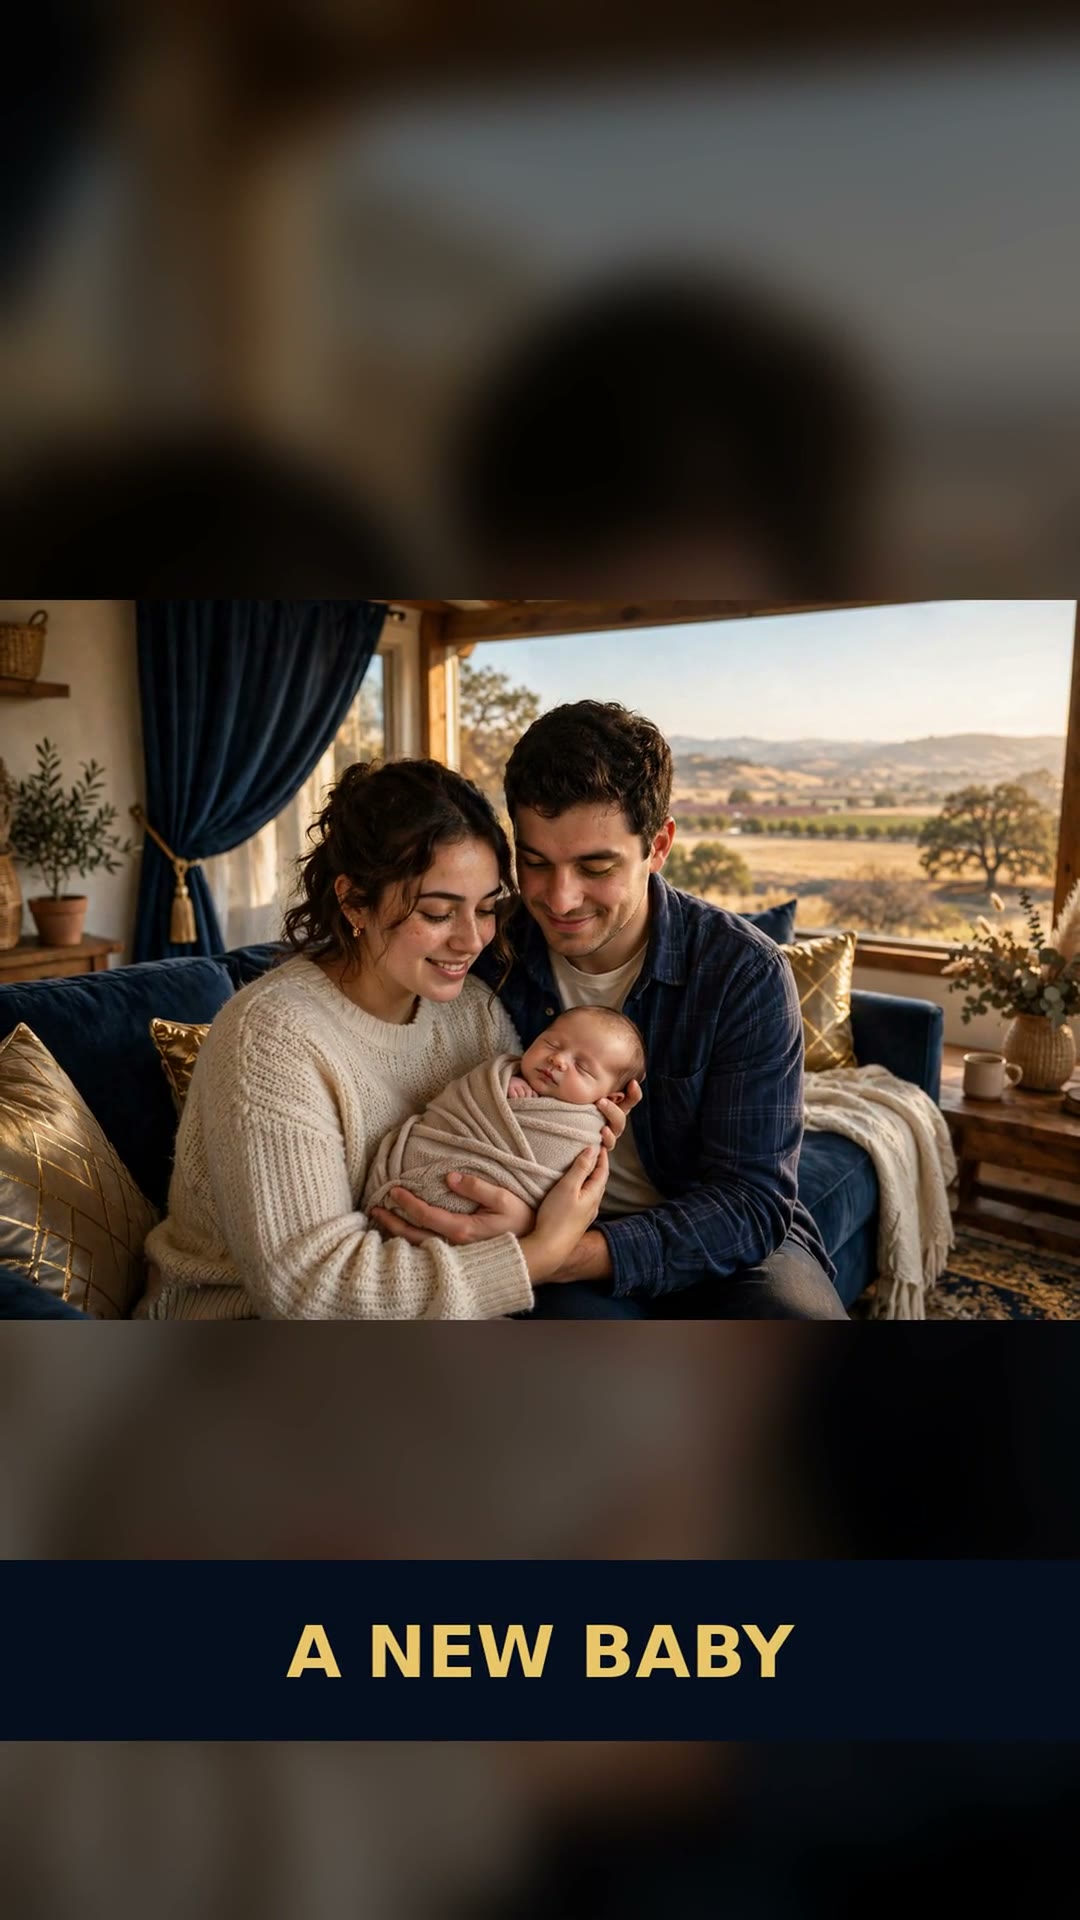
Life happens. Be ready for it.
A new baby, a new home, a new job — the moments that change your life are the moments to make sure the people counting on you are protected.
Request Your Free ReviewWays I can help protect your family
Every family’s situation is different. These are the conversations I have most often — tap any one to see what it means, in plain English.
Term Life Insurance
Straightforward coverage for a set number of years — often the most affordable way to protect your income and your home.
Learn more →Whole Life Insurance
Lifelong coverage that stays with you, with premiums that don’t change and cash value that builds over time.
Learn more →Indexed Universal Life
Permanent coverage with flexible premiums and cash value growth potential tied to a market index, subject to policy terms.
Learn more →Final Expense
A smaller, permanent policy to help cover funeral and final costs, so your family isn’t left scrambling.
Learn more →Living Benefits
Many modern policies let you access part of your benefit while you’re living, if a qualifying illness strikes.
Learn more →Mortgage Protection
Coverage designed around your home loan, so your family can stay in the home if something happens to you.
Learn more →Retirement & 401(k) Rollovers
Changed jobs or retired? I’ll help you review what you have and understand your rollover options.
Learn more →Free Policy Review
Already have coverage? Let’s look at it together — what it covers, what it doesn’t, and whether it still fits.
Learn more →Check instant term life rates on my Ethos page — coverage up to $2M, no medical exams or blood tests, with a 30-day money-back guarantee. Prefer to talk it through first? The free review is always available.
Life happens — in the best ways, and the hard ones
This short video walks through the moments families tell me about most: a new baby, a new home, a growing family. Each one is a reason to make sure your loved ones would be okay financially if you weren’t here — or if a serious illness changed everything.
- ✓A new baby — someone new is counting on your income.
- ✓A new home — a mortgage your family would still need to pay.
- ✓A growing family — bigger responsibilities call for a fresh look at coverage.
Are You Protected?
It happens in rooms like this: a family waiting in an emergency room, holding its breath — then the doctor walks in, and everything changes. But the bills don’t stop. Life insurance can’t take away the pain — it can take away the panic, and let your family grieve instead of scramble.
- ✓The mortgage — still comes due on the first, paycheck or no paycheck.
- ✓The everyday bills — the car payment right behind it, plus groceries, utilities, and gas. They all keep coming.
- ✓The breathing room — coverage that keeps a roof over your family’s head and the car in the driveway while they find their footing.
When did you last review your policy?
Most people buy life insurance once and never look at it again. But life moves — and coverage that fit five years ago may not fit today.
The work-coverage gap
Coverage through an employer is a good start, but it’s usually a small multiple of your salary, it’s rarely enough on its own — and it typically ends when the job does. A personal policy stays with you wherever you work.
Old policies, old details
Beneficiaries change. Policies get bought for one stage of life and kept into the next. A review checks who’s named, what’s covered, and whether the amount still makes sense for your family today.
Life changes everything
Marriage, a baby, a new home, a new job, a divorce, retirement — each one changes what your family needs. If any of these happened since you last looked, it’s time for a fresh review.
Myth or Fact?
From my educational Myth or Fact series — tap a card to see the answer. A lot of what people believe about life insurance turns out to be wrong.
“The life insurance I have through work is usually enough.”
Work coverage is a helpful start, but it’s often only one or two times your salary — and it usually doesn’t follow you if you leave the job. Most families need their own policy on top of it.
“Young, healthy people usually get the lowest rates.”
Age and health are two of the biggest factors in pricing. The youngest, healthiest version of you is today — which is why waiting rarely makes coverage cheaper.
“Life insurance is only for people with kids.”
If anyone depends on your income — a spouse, a parent, a partner — or if you have debts someone else would inherit, like a mortgage or a co-signed loan, coverage matters with or without kids.
Test Your Knowledge
Think you know life insurance? Four quick games, right here — no sign-up, nothing to buy. See how you score, and learn a few things that might surprise you along the way.
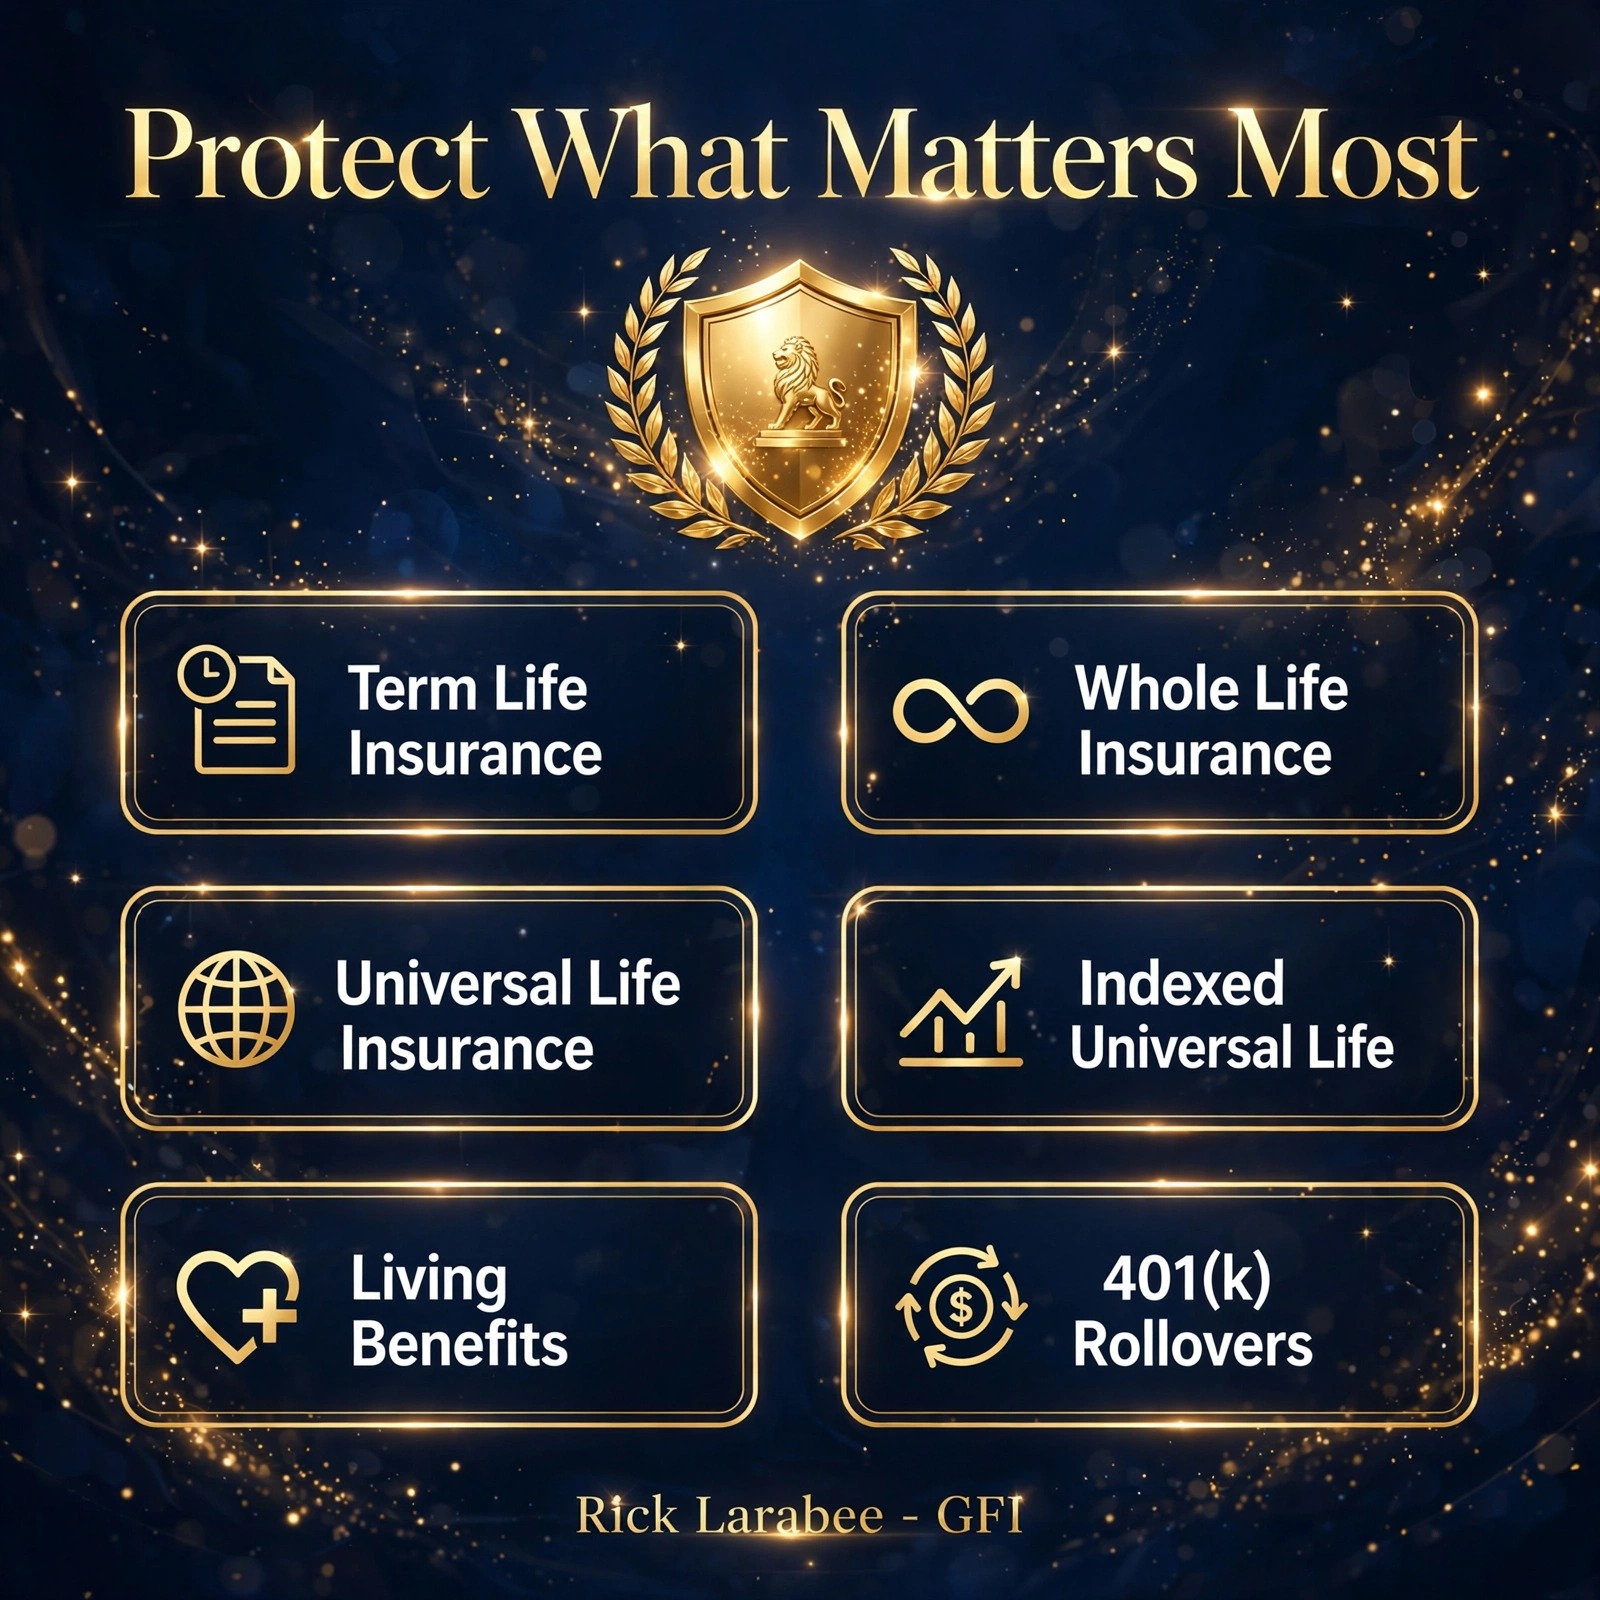
Protect what matters most
Whether it’s straightforward term coverage, a permanent policy, living benefits, or sorting out an old 401(k), the right plan starts with understanding what you already have — and what you actually need.
A short, one-on-one conversation about your family, your goals, and what you have now. No pressure, ever.
I walk you through your options in plain English — what each one does, and what it costs.
You take your time. If a policy makes sense, I help with the application. If it doesn’t, you still leave knowing where you stand.
Meet Rick
I’ve served local families here in the Central Valley for decades, and I bring that same neighbor-to-neighbor approach to insurance. No call centers, no scripts read by a stranger — when you reach out, you talk to me.
My job is simple: explain your options clearly, answer every question honestly, and let you decide at your own pace. That’s it.
Request your free policy review
Tell me a little about what you need. Submitting opens your text app with everything filled in, addressed to me at 661-690-6914 — just hit send.
Term Life Insurance
The straightforward one: coverage for a set number of years, designed to protect your family during the years they depend on you most.
Instant term life rates through Ethos — no medical exam.
What it is, in plain English
Term life covers you for a specific period — commonly 10, 20, or 30 years. If you pass away during that term, the policy pays a tax-free death benefit (in most cases) to the people you name. If the term ends, the coverage ends — which is why term is usually the most affordable way to carry a larger amount of coverage.
Who it’s often a fit for
- ✓Parents who want income protection while the kids are growing up
- ✓Homeowners who want the mortgage covered for the life of the loan
- ✓Families who want the most coverage their budget allows, right now
Good to know
Many term policies can be converted to permanent coverage later, depending on the policy’s terms. We’ll talk through term lengths and amounts based on your income, debts, and how long your family would need support.
Coverage, features, and eligibility are subject to underwriting and carrier approval. This page is educational information, not a quote or a guarantee of coverage.
See your term life rate in minutes
Check instant rates through Ethos — no medical exam — or talk it through with Rick first in a free, no-pressure review.
Whole Life Insurance
Permanent coverage that lasts your whole life — with premiums that stay the same and cash value that builds over time.
What it is, in plain English
Unlike term coverage, whole life doesn’t expire at the end of a set period — it’s designed to be there whenever your family needs it, as long as premiums are paid. Part of each premium builds cash value inside the policy, which grows on a guaranteed schedule set out in the policy.
Who it’s often a fit for
- ✓People who want coverage that never runs out
- ✓Families planning ahead for final expenses and leaving something behind
- ✓Anyone who values predictable, level premiums for life
Good to know
Whole life premiums are higher than term for the same coverage amount, because the policy is built to last. For many families, the right answer is a combination — term for the big years, whole life for the permanent piece.
Coverage, features, and eligibility are subject to underwriting and carrier approval. Cash value growth and policy guarantees are per the terms of the issued policy.
Let’s find the right coverage for your family
Free, no-pressure review with Rick — in plain English.
Indexed Universal Life (IUL)
Permanent life insurance with flexible premiums — and cash value growth potential tied to a market index, without being invested directly in the market.
What it is, in plain English
An IUL is a permanent life insurance policy — the coverage can last a lifetime — with two moving parts that make it different. First, premiums are flexible within limits. Second, the policy’s cash value can be credited interest based on the movement of a market index (such as the S&P 500). Your money is not invested directly in the market; interest crediting is subject to caps, participation rates, and other policy terms set by the carrier, and can be zero in a period when the index doesn’t perform.
Who it’s often a fit for
- ✓People who want permanent coverage with more flexibility than whole life
- ✓Families thinking long-term about building cash value inside a policy
- ✓Anyone who wants living benefits options alongside permanent coverage
Good to know — honestly
An IUL is a long-term policy, not a savings account or an investment, and how it performs depends on the policy’s terms and keeping it properly funded. I’ll walk you through an illustration line by line — including the caps and costs — so you can judge it with clear eyes.
Coverage, features, and eligibility are subject to underwriting and carrier approval. Cash value growth potential is tied to an index and subject to policy terms, caps, and participation rates; it is not guaranteed.
Let’s find the right coverage for your family
Free, no-pressure review with Rick — in plain English.
Final Expense Insurance
A smaller, permanent policy designed to help cover funeral, burial, and final costs — so your family isn’t left with the bill and the stress.
What it is, in plain English
Final expense is whole life insurance in a smaller amount, built for one job: making sure the costs at the end of life — funeral, burial or cremation, and final medical or legal bills — don’t land on the people you love. Applications are often simpler than for larger policies, and the coverage is permanent.
Who it’s often a fit for
- ✓Seniors who want their final arrangements taken care of in advance
- ✓Adult children helping a parent put a plan in place
- ✓Anyone whose savings wouldn’t comfortably cover final costs
Good to know
Some final expense policies have a graded or waiting period before the full benefit is payable for natural causes. I’ll explain exactly how any policy you’re considering works before you decide anything.
Coverage, features, and eligibility are subject to underwriting and carrier approval.
Let’s find the right coverage for your family
Free, no-pressure review with Rick — in plain English.
Living Benefits
Life insurance you don’t have to die to use. Many modern policies can pay out part of the benefit while you’re living, if a qualifying illness or injury strikes.
What it is, in plain English
Living benefits are features — often called accelerated benefit riders — built into many newer life insurance policies. If you’re diagnosed with a qualifying critical, chronic, or terminal condition (things like a heart attack, stroke, or cancer, depending on the policy), you may be able to access a portion of your death benefit early, while you’re still living, to help with medical bills, household expenses, or time away from work.
Why families ask about it
- ✓A serious illness often hits income and savings at the same time
- ✓Health insurance doesn’t cover everything — deductibles, travel, lost wages, help at home
- ✓Older policies usually don’t include these features — a review can show what you have
Good to know
Qualifying conditions, amounts, and terms vary by policy and carrier, and using a living benefit reduces the death benefit that remains. I’ll show you exactly what any policy includes, in writing, before you decide.
Coverage, features, and eligibility are subject to underwriting and carrier approval. Rider availability and qualifying conditions vary by carrier and policy.
Let’s find the right coverage for your family
Free, no-pressure review with Rick — in plain English.
Mortgage Protection
Coverage built around your home loan — so if something happens to you, your family can keep the home.
What it is, in plain English
Mortgage protection is life insurance sized and timed around your mortgage. If you pass away during the term, the benefit can pay off the loan or cover the payments, so your family isn’t forced to sell the home or fall behind. Many policies also offer options tied to disability or illness, depending on the carrier.
Who it’s often a fit for
- ✓New homeowners in the first years of a mortgage
- ✓Families where one income carries most of the payment
- ✓Anyone who recently refinanced and reset the clock on their loan
Good to know
Unlike lender-offered mortgage insurance, a personal policy pays the benefit to your family — not the bank — and it stays with you if you move or refinance. Your family decides how to use it.
Coverage, features, and eligibility are subject to underwriting and carrier approval.
Let’s find the right coverage for your family
Free, no-pressure review with Rick — in plain English.
Retirement & 401(k) Rollovers
Changed jobs, been laid off, or retired? Let’s look at what’s sitting in that old 401(k) — and what your options are.
What it is, in plain English
When you leave a job, your 401(k) usually stays behind with your old employer’s plan. You generally have a few choices: leave it there, roll it into a new employer’s plan, roll it into an IRA, or cash it out (which usually triggers taxes and possible penalties). A rollover moves the money into an account you control, without cashing it out.
Why people review their options
- ✓Old accounts get forgotten — sometimes across several past employers
- ✓Consolidating can make your retirement money simpler to keep track of
- ✓Some rollover options include insurance-based products with protection features worth understanding
Good to know — honestly
There’s no single right answer, and leaving money where it is is sometimes the best choice. I’ll lay out the pros and cons of each option — including fees, features, and tax considerations to discuss with your tax professional — and you decide. Nothing moves without your clear say-so.
Coverage, features, and eligibility are subject to underwriting and carrier approval. This page is educational information only and is not tax, legal, or investment advice.
Let’s take a clear look at where you stand
Free, no-pressure review with Rick — in plain English.
Free Policy Review
The best place to start — whether you have coverage already or you’re starting from zero. Free, one-on-one, and no pressure.
What happens in a review
Your current policies, your work coverage, your beneficiaries — what’s actually in place today.
Your income, your home, your family, your debts — and how those have changed since the policy was written.
Where you’re covered, where the gaps are, and what — if anything — I’d suggest. If your current coverage is right for you, I’ll tell you that, too.
Signs it’s time for a review
- ✓You can’t remember the last time you looked at your policy
- ✓You’ve married, had a child, bought a home, or changed jobs
- ✓Your only coverage is through work
- ✓Your policy is older and doesn’t mention living benefits
- ✓You’re not sure your beneficiaries are up to date
Coverage, features, and eligibility are subject to underwriting and carrier approval. A policy review is an educational conversation; it does not change or replace any existing coverage unless you choose to apply for a new policy.
Fun & Games — Test Your Knowledge
Four quick games about life insurance, in plain English. No sign-up, no cost — just a fun way to find out what you know, and pick up a few things you might not.
Game 1 — Test Your Knowledge
Ten questions, drawn fresh each game: Myth or Fact statements and quick knowledge picks. Each answer comes with a one-line explanation — take your time and read it. Right answers are worth 100 points, and streaks count.
Game 2 — Which Policy Fits?
Real-life situations, one card at a time. Pick the coverage that fits each person best — there’s one best answer per card, with the reasoning shown after you choose.
Game 3 — The Coverage Exam
Think you know life insurance? Fifteen questions, drawn fresh each exam from five topics — Coverage Types, Beneficiaries, Policy Facts, Living Benefits, and Costs & Reviews — and you’ll need 70% to pass. You get 30 seconds a question, and every answer comes with a one-line explanation that stays up long enough to read. At the end, you get your report card.
Game 4 — The Coverage Quiz
Ten questions, drawn fresh each game from a bank of twelve — beneficiaries, premiums, living benefits, and the plain-English basics every family should know. You get 20 seconds a question: right answers are worth 100 points, fast answers earn up to 50 bonus points, and three right in a row starts a +25 streak bonus. Every answer comes with a short “here’s why.”
These games are for education and fun — they aren’t advice for any one family. Coverage, features, and eligibility are subject to underwriting and carrier approval, and policy details are governed by the terms of the issued policy.
Not sure what fits your family?
Every situation is different — a free policy review sorts out what fits you. No cost, no pressure.
About Rick Larabee
Licensed Life Insurance Professional · Expansion Director with GFI — Global Financial Impact
A neighbor first, an insurance professional second
I’m Rick Larabee. For decades, families here in California’s Central Valley have trusted me to show up, do honest work, and treat them right. When I became a licensed life insurance professional, I brought that same approach with me: sit down together, talk plainly, and never pressure anybody into anything.
Most of the families I meet either have no coverage, or have a policy they bought years ago and haven’t looked at since. Either way, my job is the same — help you understand exactly where you stand, explain your options in plain English, and let you decide what’s right for your family, in your own time.
I serve families across California and Ohio, one-on-one — by phone or in person. When you call 661-690-6914, you get me. Not a call center, not a handoff.
How I work
- ✓Plain English, always. If I can’t explain it simply, we’re not done talking.
- ✓No pressure, ever. Take the information home. Talk it over. Decide when you’re ready.
- ✓Honest about fit. If what you already have is right, I’ll say so.
- ✓Here after the paperwork. Questions a year from now? Same phone number, same Rick.
Talk to Rick
Call, text, or send the form below — it opens your text app with your message ready to send to 661-690-6914.
Call or text anytime
The fastest way to reach me. If I’m with a family, leave a message and I’ll call you back personally.
661-690-6914Serving families in California & Ohio
Rick Larabee · Licensed Life Insurance Professional
GFI — Global Financial Impact
Follow along
Myth or Fact posts, family protection tips, and more: